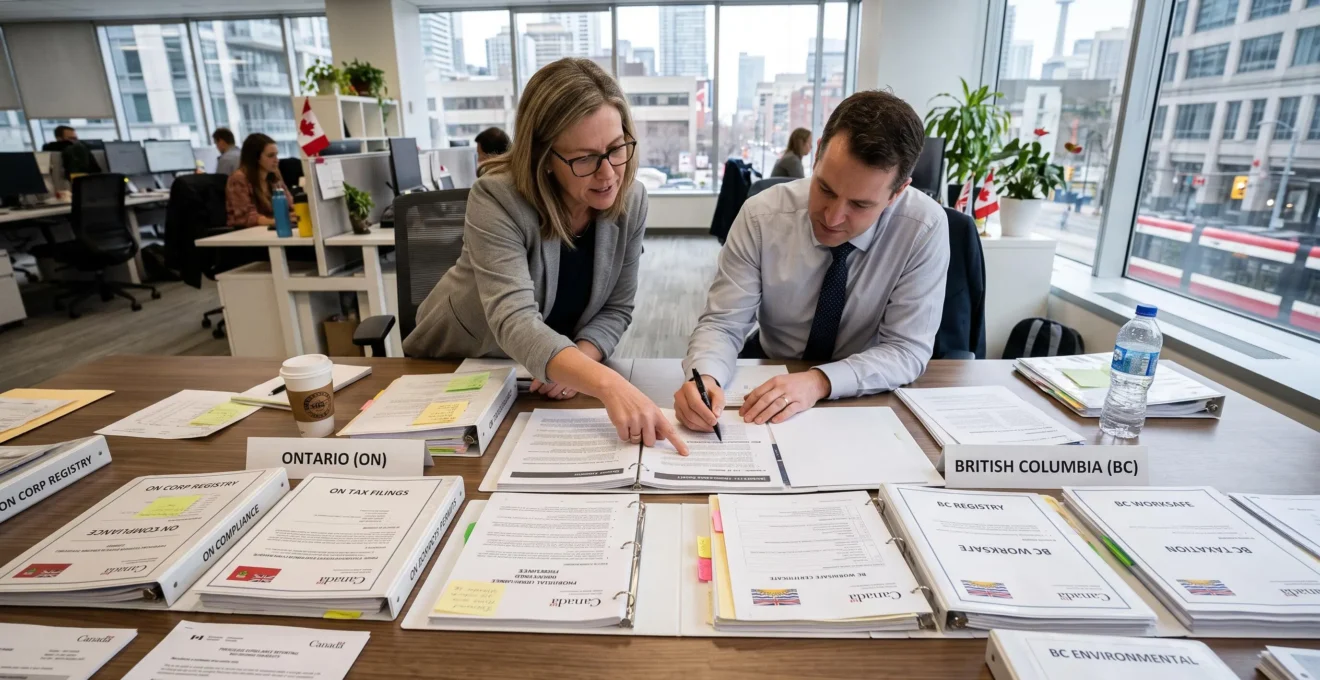
Canada offers businesses an established legal framework, recognizable regulatory institutions and formal processes for changing legislation. Yet regulatory predictability does not mean that the same requirements apply everywhere or remain unchanged throughout an investment’s lifetime. Entrepreneurs making long-term commitments must account for differences between federal, provincial and municipal rules, as well as the timing of future regulatory changes.
The practical question is not simply whether Canadian regulation is stable. It is whether a business can identify its obligations, anticipate changes and absorb compliance costs without undermining its investment strategy. A company planning to hire employees, enter additional provinces or raise external capital may face different regulatory requirements at each stage.
Effective long-term business planning therefore treats regulatory compliance as an operating and investment consideration rather than a one-time administrative task. The most useful approach combines jurisdiction mapping, systematic monitoring, expansion readiness and periodic reassessment of the business’s legal structure.
Canadian regulatory planning: Key points
- Canada’s federal structure creates different regulatory obligations across provinces, making jurisdiction-specific planning essential.
- Regulatory predictability depends on monitoring official changes, checking effective dates and budgeting for implementation.
- Business structure, incorporation jurisdiction and expansion plans should be evaluated together over a multi-year horizon.
- Why Can the Same Business Face Different Rules Across Canadian Provinces?
- How to Monitor Regulatory Changes Affecting a Small Canadian Business?
- Federal or Provincial Rules: Which Apply to Your Business Activities in Canada?
- The Compliance Oversights That Can Delay Expansion Into Another Province
- When Should a Growing Canadian Business Review Its Compliance Obligations?
- Why Can Contract Rules Differ Between Quebec and Other Canadian Provinces?
- Federal or Provincial Incorporation: Which Better Fits Your Expansion Plans?
- Sole Proprietorship, Partnership or Corporation: Which Structure Fits Your Canadian Business?
Why Can the Same Business Face Different Rules Across Canadian Provinces?
The same business can face different rules across Canadian provinces because legislative authority is divided between the federal government and provincial governments. The Constitution Act, 1867 establishes this division, allowing provinces to regulate important aspects of commercial activity independently. Consequently, employment obligations, taxation, business registration and commercial practices may vary according to where a company operates.
This constitutional arrangement is a fundamental feature of Canada’s regulatory environment, not necessarily evidence of unpredictable policymaking. Businesses can often identify the governing institutions in advance, but national expansion may require managing several regulatory systems simultaneously.
Federal jurisdiction covers particular industries and activities. Banking, telecommunications, air transportation and interprovincial transportation are among the industries identified in the Government of Canada‘s list of federally regulated industries and workplaces. The list specifically addresses federal labour jurisdiction; it does not mean that these businesses are exempt from every provincial law.
For businesses outside federal labour jurisdiction, provincial employment standards generally govern matters such as statutory holidays, working hours and termination requirements. Provinces also maintain different approaches to business licensing and certain sales taxes.
Quebec introduces another important distinction. Its civil law tradition affects private-law relationships, while the Charter of the French Language creates language requirements that businesses must assess when entering the Quebec market. Other provinces generally operate under common law for private-law matters.
Sales tax arrangements also differ. Depending on the province and applicable transaction, businesses may encounter the Harmonized Sales Tax (HST), separate provincial sales taxes (PST) or Quebec Sales Tax (QST). Federal GST/HST obligations must be assessed alongside any relevant provincial requirements.
A practical way to map these differences is to separate business activities before assigning regulatory responsibility.
| Business activity | Regulatory questions to examine | Planning implication |
|---|---|---|
| Hiring employees | Does federal or provincial employment legislation govern the workplace? | Adapt employment contracts, payroll processes and workplace policies. |
| Selling products or services | Which sales tax, consumer protection and sector-specific rules apply? | Configure transaction systems and commercial documentation. |
| Establishing a business presence | Is extra-provincial registration or a local licence required? | Allocate administrative costs and registration time. |
| Marketing nationally | Which federal and provincial advertising, privacy and language requirements apply? | Review campaigns and customer communications before launch. |
For long-term budgeting, these differences create a need for province-specific legal reviews, system configuration and administrative resources. A single national compliance policy can provide common principles, but its implementation may require local variations.
Once the jurisdictional differences are understood, the next challenge is maintaining that understanding as regulations evolve.
How to Monitor Regulatory Changes Affecting a Small Canadian Business?
A small Canadian business can monitor regulatory changes effectively by combining official government publications with sector-specific alerts and a documented review process. The objective is not to track every legislative development, but to identify relevant proposals, distinguish them from enforceable requirements and assess how much preparation time each change allows before affecting operations.
Federal regulatory monitoring should begin with official government publications. The Department of Justice explanation of how Canadian laws and regulations are created distinguishes the stages through which federal legislation and regulations develop.
For federal regulations, the Canada Gazette, Part I publishes proposals that may be open for public comment. Part II publishes final regulations. Businesses should also check legislation and associated commencement provisions because Royal Assent, publication and legal enforceability do not necessarily occur on the same date.
At the provincial level, legislative assembly records, official statutes and regulations databases, government notices and provincial gazettes provide complementary information. Municipal bylaw portals matter when business operations depend on local zoning, permits or other municipal requirements.
Industry associations, professional accountants and legal advisors can help filter this information. However, an industry newsletter should not be treated as a substitute for checking an official publication when the timing or applicability of a change matters to an investment decision.
A simple tracking register should record the responsible authority, relevant activity, current legislative status, effective date, transitional arrangements and person responsible for implementation.
For prioritization, three criteria are particularly useful:
- Applicability: Does the change directly affect the business’s industry, workforce, customers or operating locations?
- Adaptation cost: Will implementation require new systems, contracts, employee training or professional advice?
- Preparation time: How long remains before the requirement becomes applicable or enforceable?
A proposal with substantial operational implications may justify early budgeting, even when its final wording is uncertain. Conversely, a finalized requirement unrelated to the company’s activities may require only documentation of its non-applicability.
Small businesses can also participate in relevant consultations and establish arrangements with advisors to flag changes affecting their sector. The purpose is to improve preparation, not to assume that proposed regulations will necessarily become law in their original form.
Monitoring becomes most valuable when the business first identifies which regulatory authorities actually govern its operations.
Federal or Provincial Rules: Which Apply to Your Business Activities in Canada?
Federal or provincial rules apply to a Canadian business according to the activity being regulated, not simply the location of its headquarters or incorporation. Banking, telecommunications, airlines and certain interprovincial transportation businesses fall under federal labour jurisdiction. Most other workplaces follow provincial or territorial employment standards, while several federal and provincial laws can apply to the same business simultaneously.
This distinction matters because jurisdiction is not necessarily determined company-wide. A business must examine employment, commercial transactions, personal information, taxation and corporate registration separately.
For instance, a provincially regulated retailer may need to comply with federal requirements governing certain commercial activities while following provincial employment standards for its workers.
Privacy law illustrates the potential overlap. The Personal Information Protection and Electronic Documents Act (PIPEDA) generally governs specified private-sector commercial personal-information activities, subject to its statutory scope and applicable exemptions. Alberta, British Columbia and Quebec have substantially similar private-sector privacy legislation that can govern certain activities within those provinces. PIPEDA may still apply to interprovincial or international personal-information transactions and other activities within its scope.
Quebec’s Law 25 strengthened the province’s private-sector privacy framework. It should not be interpreted as removing every possible federal privacy obligation from businesses operating in Quebec.
Likewise, incorporating federally does not automatically place an ordinary retailer, manufacturer or consulting business under federal employment standards.
The following distinction helps prevent misclassification:
| Activity or industry | Primary jurisdictional consideration | Additional review |
|---|---|---|
| Banking and telecommunications | Federal labour jurisdiction for covered activities | Other applicable federal and provincial obligations |
| Interprovincial trucking | Federal labour jurisdiction where the operation meets the relevant criteria | Transportation, safety and other operational requirements |
| Local retail business | Generally provincial employment standards | Federal and provincial taxes, consumer rules and privacy |
| Customer data processing | Applicable federal and provincial privacy legislation | Location, type of activity and data transactions |
| Corporate registration | Federal or provincial incorporation framework | Local registration and licensing obligations |
Before committing capital, an entrepreneur should document the company’s products, workforce arrangements, financing activities and data practices. Each category can then be matched to the relevant legislation and verified through the responsible regulator, provincial registry or qualified advisor.
Incorrect classification can result in unsuitable employment policies, missing registrations or budgets based on the wrong compliance assumptions. The financial risk arises not only from potential enforcement consequences but also from the cost of correcting operational systems after investment.
Once the applicable rules are identified, they should be converted into practical requirements before operations begin in another province.
The Compliance Oversights That Can Delay Expansion Into Another Province
Expanding into another Canadian province can create compliance delays when a company assumes its existing registrations, employment policies and administrative systems automatically remain sufficient. Extra-provincial registration, tax obligations, workplace insurance, licensing and local language requirements may need separate attention. Addressing these issues before launch reduces the risk of discovering unexpected conditions after resources have already been committed.
Corporate registration is a common starting point. A company incorporated federally or in one province may need to register in another jurisdiction where it carries on business. The applicable legal test, exemptions, procedures and fees depend on the destination province and the company’s activities.
The Corporations Canada guidance on registering a federal corporation in a province or territory explains that federal incorporation does not remove provincial or territorial registration obligations. Businesses should confirm the current requirements directly with the relevant registry.
Registration is only one part of the expansion process. The company must also assess whether it needs additional sales tax accounts, employer registrations, workplace insurance coverage or sector-specific permissions.
Workers’ compensation illustrates why existing administrative arrangements should not be assumed to transfer unchanged. Employers operating in Ontario may need to assess registration with the Workplace Safety and Insurance Board (WSIB), while activities in British Columbia may require registration with WorkSafeBC. Coverage and registration depend on the applicable rules and business circumstances.
Employment agreements, leave provisions, termination procedures and payroll administration also require review for the destination jurisdiction.
Quebec expansion adds a potentially significant language-compliance workstream. Depending on the business and the applicable provisions of the Charter of the French Language, commercial contracts, signage, websites, employee communications and other materials may need adaptation. The specific requirements should be verified before commissioning translations or finalizing commercial documentation.
A hypothetical example illustrates the sequencing risk. An Ontario-based company budgets for a British Columbia launch, signs premises-related commitments and hires local staff, but reviews provincial registrations and employment obligations only immediately before opening. Even without an enforcement action, additional administrative steps could disrupt the planned opening date.
Five actions to complete before entering a new province
- Confirm whether extra-provincial registration is required and save a written registry assessment with any necessary filing confirmation.
- Review applicable federal and provincial sales tax requirements and produce a tax-registration decision record.
- Verify employer, payroll and workers’ compensation obligations and maintain a jurisdiction-specific employer compliance checklist.
- Review employment agreements, commercial contracts and applicable language requirements, producing approved local document versions where necessary.
- Assign owners and completion dates to outstanding requirements and create a signed pre-launch compliance register.
These actions form a practical internal planning checklist, not a universal government-mandated procedure. The underlying legal requirements still depend on the business and jurisdiction.
As a company continues growing, the same principle applies beyond geographic expansion: new business milestones can activate obligations that did not exist at startup.
When Should a Growing Canadian Business Review Its Compliance Obligations?
A growing Canadian business should review its compliance obligations whenever a material operational change occurs, supported by a broader periodic review. Hiring employees, entering another province, launching regulated products, changing ownership or crossing a relevant regulatory threshold can create new requirements. Reviewing these events before implementation is generally more useful than relying exclusively on an annual compliance exercise.
A startup’s original compliance framework may have been appropriate for an owner-operated business serving one local market. It may become inadequate after the company hires workers, establishes additional premises or begins handling different categories of customer information.
Growth can therefore increase regulatory exposure even when the underlying legislation has not changed. The business has changed, causing previously irrelevant obligations to become applicable.
Particularly important review triggers include:
- Hiring the first employee or establishing a workforce in another jurisdiction.
- Introducing a new product or service subject to sector-specific requirements.
- Reaching a revenue, workforce or operational threshold relevant to a particular program or rule.
- Changing the business’s legal structure or ownership arrangements.
- Entering a new distribution market or adopting a different personal-information processing model.
An annual full-scope review synchronized with financial planning provides a useful internal discipline. It can be supplemented by shorter assessments before material business decisions. This schedule is a recommended management practice, not a general statutory requirement.
A productive review should answer two distinct questions. First, is the business still meeting obligations already identified? Second, have new activities or legal developments created obligations that have never been recorded?
The second question is particularly important because reviewing only the existing compliance register cannot reveal requirements that the company overlooked when designing it.
Documentation should include review dates, responsible personnel, sources checked, identified gaps and actions completed. These records can support lender, investor or purchaser due diligence by demonstrating that management actively assesses regulatory exposure.
However, documented reviews do not guarantee better financing terms or an unqualified due diligence outcome. Their practical value depends on the quality of the assessment and whether identified issues have been resolved.
One area where periodic review becomes especially important is the legal enforceability of agreements across different provincial legal systems.
Why Can Contract Rules Differ Between Quebec and Other Canadian Provinces?
Contract rules differ between Quebec and other Canadian provinces primarily because Quebec generally follows civil law for private-law matters, while the other provinces generally follow common law. Quebec’s Civil Code establishes codified rules governing contractual obligations, interpretation and remedies. Common law jurisdictions place greater reliance on judicial precedent, although legislation also plays an important role in their contract law.
This distinction affects contract drafting even when two businesses intend to create commercially similar arrangements.
For example, legal concepts and standard clauses developed for a common law agreement may not operate identically under Quebec’s Civil Code. Contractual remedies, obligations to perform, interpretation principles and provisions dealing with unexpected events can require jurisdiction-specific analysis.
Force majeure is one example. Quebec’s Civil Code contains provisions relevant to the consequences of superior force, while common law approaches depend significantly on the contractual language and applicable legal doctrines. Using identical wording across provinces does not necessarily produce identical results.
Businesses should therefore be cautious about copying a contract template created for one provincial legal environment into another without review.
Consumer protection adds another layer. Quebec’s Consumer Protection Act contains mandatory requirements that may affect consumer contracts, warranties, disclosure obligations and cancellation rights. Where mandatory legislation applies, negotiated contractual provisions cannot necessarily override those protections.
Language requirements also matter in Quebec. Depending on the type of contract and applicable statutory provisions, the Charter of the French Language may affect the language in which contracts and supporting documentation must be provided.
A company seeking standardized national contracts can consider two approaches:
| Planning consideration | Province-specific templates | National template with local validation |
|---|---|---|
| Legal adaptation | Clauses tailored to applicable provincial requirements | Shared provisions reviewed for local compatibility |
| Administration | Several document versions to maintain | Centralized drafting with jurisdiction-specific adjustments |
| Change management | Updates can target affected jurisdictions | Changes may require review across multiple jurisdictions |
| Scalability | Useful where substantive legal differences are significant | Useful where obligations can be accommodated without compromising enforceability |
Neither approach automatically guarantees compliance. A contract designed around the strictest identified requirement may still contain concepts that operate differently under another province’s law.
For long-term planning, legal review expenses and contract maintenance should be considered alongside the operational benefits of document standardization.
Contract architecture is one component of expansion readiness; the jurisdiction in which the business incorporates is another decision with long-term implications.
Federal or Provincial Incorporation: Which Better Fits Your Expansion Plans?
Federal incorporation may suit a Canadian business planning a national corporate identity or operations in several provinces, while provincial incorporation may be practical for a company expecting to operate mainly within one jurisdiction. Neither option automatically removes the need for provincial registration, business licences or local compliance. The better choice depends on growth plans, corporate naming requirements and ongoing administrative responsibilities.
Federal incorporation under the Canada Business Corporations Act creates a corporation governed by federal corporate legislation. Provincial incorporation creates a corporation under the applicable provincial statute.
Both routes can support legitimate commercial activities and future expansion. However, their corporate-law requirements, naming procedures and administrative obligations differ.
Federal incorporation offers a framework for national corporate naming protection, subject to applicable legal conditions. Provincial incorporation generally provides naming rights through the relevant provincial regime, although business name, trademark and corporate name rights should not be confused.
Importantly, federal incorporation does not remove provincial or territorial registration requirements where the corporation carries on business. It also does not eliminate provincial employment, licensing or other applicable operational obligations.
Businesses should therefore compare more than the initial incorporation fee. Their planning model should consider annual filings, provincial registrations, professional services, corporate records and future changes in jurisdiction.
| Decision factor | Federal incorporation | Provincial incorporation |
|---|---|---|
| Corporate legislation | Federal corporate statute | Applicable provincial corporate statute |
| Corporate name considerations | Federal naming review and protection framework | Provincial naming framework |
| Expansion into other provinces | Extra-provincial registration may still be required | Extra-provincial registration may still be required |
| Administrative obligations | Federal corporate filings plus applicable provincial requirements | Provincial corporate filings plus requirements elsewhere |
| Typical planning rationale | National branding and multi-jurisdiction corporate strategy | Concentrated provincial operations and locally aligned administration |
Federal incorporation does not automatically make fundraising easier. Investors may evaluate governance, share structure, jurisdictional familiarity, tax considerations and transaction-specific needs rather than preferring one incorporation regime universally.
Changing corporate jurisdiction later may be possible through a continuation process, subject to the relevant statutes and procedural requirements. However, that change can involve professional work, filings and coordination, making the initial decision worth evaluating carefully.
A useful planning horizon is the next three to five years. Entrepreneurs can compare expected operating provinces, capital-raising plans, ownership changes and corporate naming needs under each route. This horizon is a strategic recommendation, not a prescribed legal period.
The incorporation jurisdiction matters, but it should be assessed together with the more fundamental decision of whether the business should operate as a sole proprietorship, partnership or corporation.
Key takeaways before choosing a business structure
- Evaluate legal liability and ownership flexibility alongside registration and compliance costs.
- Match the intended structure to future hiring, geographic expansion, investment and succession milestones.
- Consider the administrative work required to change structures later, rather than selecting solely for the lowest startup complexity.
Sole Proprietorship, Partnership or Corporation: Which Structure Fits Your Canadian Business?
A sole proprietorship may fit an individual entrepreneur seeking relatively simple administration, a partnership may suit people operating a business together, and a corporation may be appropriate when separate legal personality, share ownership and longer-term financing flexibility are priorities. The right choice depends on liability exposure, governance needs, taxation, provincial requirements and the business’s anticipated growth.
A sole proprietorship does not create a separate legal entity from its owner. The proprietor is generally personally responsible for business obligations, subject to the particular legal circumstances. Provincial registration requirements can apply, including rules concerning business names and local activities.
Partnerships provide a framework for conducting business with other participants. Their legal treatment, registration requirements and potential liability consequences depend on the partnership form and governing legislation.
For a partnership expecting additional owners, a carefully drafted agreement becomes particularly important. Governance arrangements should address decision-making, contributions, profit allocation, departures and dispute resolution.
Incorporation creates a separate legal entity. Shareholders generally benefit from limited liability, but this protection has exceptions. Personal guarantees, director responsibilities and applicable statutory liabilities can still expose individuals to financial obligations.
Corporations also have ongoing responsibilities, including applicable annual filings, corporate record-keeping and governance procedures.
From a financing perspective, corporate share structures can offer options for bringing in investors or adjusting ownership. A sole proprietorship cannot issue shares, while ownership arrangements in partnerships depend on their legal and contractual framework.
Taxation is another important consideration. Corporate income is subject to corporate taxation, and qualifying Canadian-controlled private corporations may benefit from the small business deduction on eligible active business income. Eligibility, rates and related provincial treatment depend on current legislation and the corporation’s circumstances.
Generalized tax comparisons should not replace calculations based on the entrepreneur’s expected income, reinvestment plans, compensation needs and applicable federal and provincial rules.
The Innovation, Science and Economic Development Canada‘s guidance on business structures explains the distinctions between unincorporated arrangements and incorporated entities, including their implications for liability, governance and financing. Although the resource focuses on social enterprises, several of its structural principles also apply more broadly.
| Criterion | Sole proprietorship | Partnership | Corporation |
|---|---|---|---|
| Legal identity | Not separate from the proprietor | Depends on applicable partnership law and form | Separate legal entity |
| Liability exposure | Generally personal | Depends on partnership type and governing rules | Generally limited for shareholders, with exceptions |
| Ownership flexibility | Single proprietor | Multiple partners under applicable arrangements | Share-based ownership |
| Ongoing administration | Often comparatively straightforward | Registration and partnership governance | Corporate filings, governance and records |
| Expansion considerations | Personal exposure and local registration | Partner coordination and multi-jurisdiction obligations | Corporate registrations and ongoing compliance |
Structure selection should be connected to identifiable business milestones. The first employee may introduce employer obligations, entering a second province may require additional registrations, and bringing in outside investors may create ownership or governance needs that the existing structure cannot efficiently accommodate.
A potential business sale or succession arrangement can introduce further considerations concerning ownership transfer, tax treatment and corporate organization.
Changing structures can be possible, but a transition may carry tax, contractual, registration and administrative implications. Entrepreneurs should evaluate those consequences before assuming conversion will be simple or inexpensive.
Before committing significant capital, prepare a multi-year operating plan that identifies expected provinces, staffing milestones, financing requirements and ownership changes. Then compare the legal structures against that plan, with jurisdiction-specific professional advice where the potential consequences are material.
Is Canada’s regulatory environment predictable enough for long-term investment?
Canada provides established legal institutions and formal processes for adopting and changing legislation. These mechanisms can help businesses monitor regulatory developments, but they do not guarantee that requirements will remain unchanged. Investment planning should therefore distinguish institutional predictability from the cost and uncertainty of future regulatory changes, especially when operating across several provinces.
Can a foreign-owned business incorporate in Canada?
Foreign ownership is possible under Canadian corporate frameworks, but applicable incorporation conditions, director requirements, investment review obligations and sector-specific restrictions must be assessed. Rules differ by jurisdiction and activity. Foreign entrepreneurs should also distinguish corporate incorporation from immigration authorization, tax residency and the right of individuals to work in Canada.
Does selling online to customers in another province automatically require extra-provincial registration?
Not necessarily. Registration depends on the applicable province’s definition of carrying on business and the company’s actual activities. Selling remotely, maintaining a physical establishment, employing local staff and conducting other operations may have different implications. Online sales can also create tax, consumer protection and privacy obligations independently of corporate registration.
How should regulatory uncertainty be reflected in a business investment budget?
Businesses can separate confirmed compliance expenses from potential costs associated with proposed changes. A planning model may include legal reviews, registration expenses, systems adaptation, training and contingency allowances, with assumptions documented for each jurisdiction. Scenario analysis can then test how regulatory delays or new obligations might affect projected cash flow without presenting uncertain outcomes as established costs.
Are regulatory compliance costs the same for every Canadian small business?
No. Compliance requirements depend on the industry, legal structure, workforce, locations, transactions and applicable regulations. A locally operated service business may have a different compliance profile from a regulated transportation provider or a retailer operating in several provinces. A useful budget must therefore be based on the business’s specific activities rather than an assumed national average.